
 English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


ABB reported first-quarter revenue of $8.734 billion, representing year-over-year growth of 18% or 11% on a comparable basis, while the company also beat the analyst consensus of $8.43 billion. Profitability was even stronger, with operating EBITA reaching $2.049 billion against expectations of $1.96 billion, and the margin increased to 23.5%. Beneath the headline numbers, the picture was equally compelling, with operating income reaching $1.780 billion on a 20.4% margin, basic earnings per share rising to $0.73*, and cash flow from operating activities increasing by 50% to $1.029 billion. It is precisely this combination of revenue growth, improved margins, and strong cash generation that makes this quarter one of the company’s most compelling results in recent times.[1]
Data centers are becoming a new growth engine
The most important takeaway from the results is that data centers are becoming one of ABB’s main growth drivers. Strong demand came from projects linked to the expansion of AI infrastructure, and according to analyst estimates, orders in this area grew at a triple-digit rate, which is an exceptionally strong signal of where capital expenditures are shifting today.[2]
This is significant because ABB is neither a chip manufacturer nor a cloud platform operator, but a supplier of electrification and automation solutions, without which the construction and operation of large data centers cannot proceed. The growth of AI is thus increasingly evident in areas such as power supply systems, distribution equipment, energy management, and the modernization of electrical grids.
Record orders supported a higher outlook
The strongest argument for the improved outlook was not just current revenue, but especially orders, which reached a record $11.298 billion and grew by 32% year-over-year, or 24% on a comparable basis. The book-to-bill ratio reached 1.29, meaning the company received significantly more new work than it could convert into revenue during the quarter, thereby creating a strong foundation for the coming quarters. The Electrification division saw particularly strong growth, with comparable orders jumping 44%, while other segments, such as Motion and Process Automation, also recorded growth. This suggests that demand is not coming from just one narrow market but is spread more broadly across key business areas.1
The company has raised its full-year ambitions
Following a strong start to the year, ABB has raised its full-year outlook and now expects revenue growth in the range of the high single digits to the low double digits. At the beginning of the year, the company had anticipated comparable growth of 6 to 9%, so this represents a significant improvement in expectations at a time when the global business environment remains uncertain. It is also important to note that the upward revision does not come amid an ideal macroeconomic environment. The company made this move despite heightened geopolitical uncertainty and volatility in global trade, suggesting that management views demand for electrification and automation as sufficiently resilient and underpinned by longer-term trends.[3]
Shares received a new boost
The positive reaction was immediately reflected in the market, where ABB shares rose by approximately 5.9%* in early trading following the release of the results. This movement is particularly significant because it reflects not only satisfaction with a single quarter but also that investors are reassessing the company’s growth profile following signs of stronger demand from the data center sector.
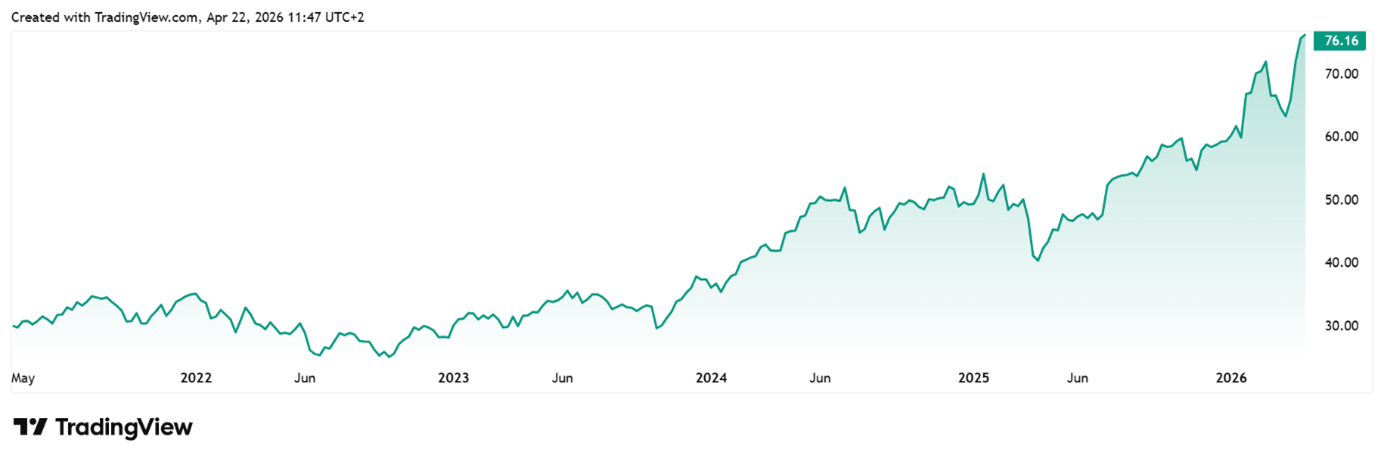
ABB share price performance over the past five years*
Looking at the broader context, this also fits into the trend from the start of the year, when ABB shares already jumped 9.6%* following fourth-quarter results in response to strong orders and a confident outlook. The current growth thus does not appear to be an isolated fluctuation, but rather a continuation of a narrative in which the market is gradually recognizing the company’s greater exposure to the growth of AI infrastructure and electrification.[4]
InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava - Staré Mesto district 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.
CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments and Supplements to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia-PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.
* Past performance is no guarantee of future results.
[1] https://new.abb.com/news/detail/135137/q1-2026-results
[2] https://finimize.com/content/abb-lifted-its-2026-sales-growth-target-on-ai-data-center-demand
[3] https://www.investing.com/news/earnings/abb-beats-q1-expectations-and-lifts-guidance-on-robust-data-center-demand-4628071
[4] https://www.reuters.com/business/abb-gives-confident-outlook-2026-2026-01-29/



