
 English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


Strategic Partnership with the Pentagon
Geopolitical tensions in the Middle East act as a direct growth catalyst for Palantir, as investors expect a massive increase in U.S. military spending and further lucrative contracts for companies closely cooperating with intelligence services. Palantir is not a newcomer in this sector – approximately 60% of its revenue comes directly from the U.S. government. The company significantly strengthened its position in 2025 by signing a massive $10 billion contract with the U.S. Army, which includes the delivery of AI analytical tools and advanced weapons-targeting systems. The fact that these technologies have been directly deployed in current operations in Iran only confirms their critical importance for national security.
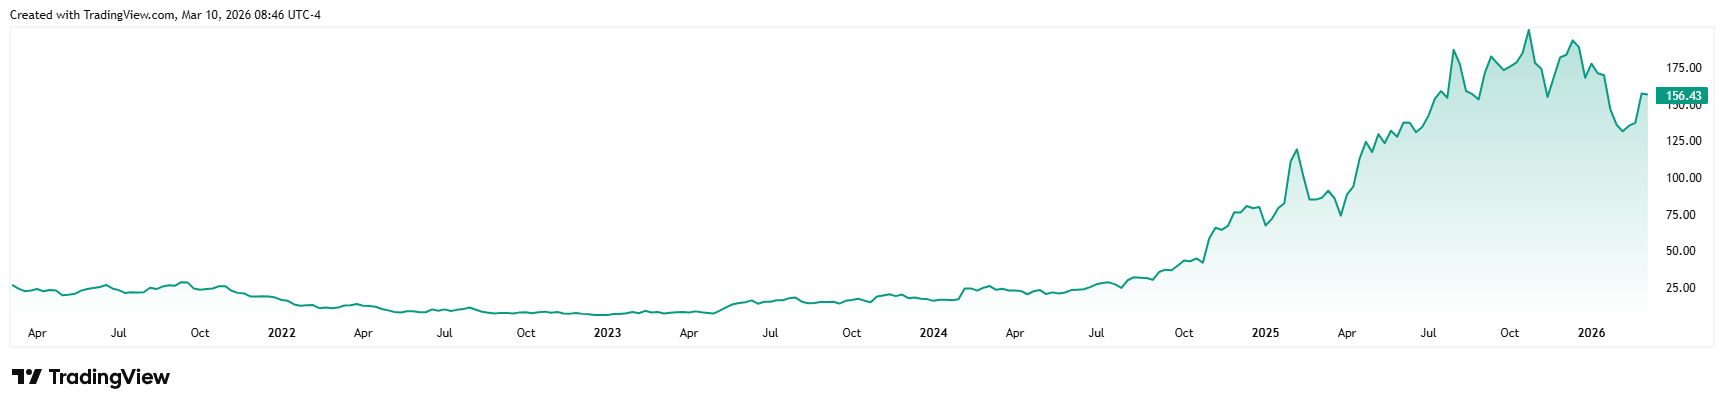
Performance of Palantir’s stock price over the last 5 years*
The Anthropic dilemma
In recent days, the market has also been shaken by the news that Anthropic has been placed on the Pentagon’s blacklist due to supply chain risks and disagreements regarding the ethics of using AI in autonomous weapons. Although Palantir worked closely with Anthropic’s Claude model within a partnership with Amazon Web Services, investors currently perceive this complication only as a temporary issue. Analysts emphasize that Palantir is essentially model-agnostic – its platforms are capable of integrating any top-tier AI model. If Claude drops out, another system will replace it. Although integrating new capacity may take time, the company’s ability to quickly rotate between AI model providers is seen as a key competitive advantage.
Optimistic outlook from analysts
Palantir’s performance sharply contrasts with the rest of the technology sector. While the Nasdaq index fell by 1.2% under pressure from rising oil prices and weaker labor market data, the software sector as a whole revived.* Palantir, together with companies such as CrowdStrike and ServiceNow, pushed software ETFs up by 8%. This trend has not gone unnoticed by major investment houses. Rosenblatt raised its price target for Palantir from $150 to $200 with a clear “Buy” recommendation, while Piper Sandler is aiming even higher with a target of $230.[1] Analysts agree that as long as the world seeks stability in technologies capable of predicting threats, Palantir’s revenues will tend to grow.
A future defined by AI and defense
In 2026, Palantir has definitively stepped out of the shadow of a controversial analytics company and has become an indispensable tool of global security. The conflict in the Middle East and the technological arms race have created ideal conditions for the company’s expansion. For investors, Palantir represents a unique hybrid – a growth technology stock with the security characteristics of a government contractor.
* Data related to the past are not a guarantee of future returns.
[1] Forward-looking statements represent assumptions and current expectations that may not be accurate or may be based on the current economic environment, which may change. These statements do not guarantee future performance. Forward-looking statements by their nature involve risk and uncertainty because they relate to future events and circumstances that cannot be predicted, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.
Notice! This marketing material is not and must not be interpreted as investment advice. Data related to the past are not a guarantee of future returns. Investing in foreign currency may affect returns due to fluctuations. All securities transactions may result in both gains and losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or may be based on the current economic environment, which may change. These statements do not guarantee future performance. InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia.
Performance of the Nasdaq 100 index over the last 5 years: https://www.tradingview.com/symbols/NASDAQ-NDX/?timeframe=60M
Performance of the software ETF over the last 5 years: https://www.ishares.com/us/products/239771/ishares-north-american-techsoftware-etf
Sources:
https://www.cnbc.com/2025/08/01/palantir-lands-10-billion-army-software-and-data-contract.html
https://www.cnbc.com/2026/02/23/anthropic-ai-dario-defense-secretary-pete-hegseth.html
InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto city district 811 02. The company is registered in the Commercial Register of the Bratislava III Municipal Court, section: Sa, file number: 4295/B, Company ID: 36 853 054, Tax ID: 2022505419.
CAPITAL MARKETS, o.c.p., a.s. is a securities trader pursuant to § 55 paragraph 1 of Act No. 566/2001 Coll. on Securities and Investment Services and on amendments and supplements to certain acts, as amended (hereinafter the Securities Act). CAPITAL MARKETS, o.c.p., a.s. was granted a license to provide investment services by the decision of the National Bank of Slovakia No. OPK-2297/2007-PLP on 30 October 2007 in accordance with § 54 paragraph 2 in conjunction with § 59 paragraphs 2 and 3 of the Securities Act, which was extended in accordance with the provisions of the Securities Act by decision No. OPK-1830/2008-PLP dated 21 April 2008, decision No. OPK-11601-1/2008 dated 28 January 2009, decision No. ODT-5059-3/2012 dated 23 July 2012 and decision No. ODT-9332/2014-1 dated 21 October 2014.



