
 English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


AMD's data centre revenues disappointed
AMD's performance in its core data center segment fell short of expectations, especially in terms of revenue. Despite reporting robust year-over-year revenue growth of 69% in the fourth quarter of 2024, the company fell short of forecasts. According to its earnings results, released on February 4, 2025, data center revenue reached a record $3.86 billion. However, analysts, according to Bloomberg, were expecting more than $4 billion. For the full year 2024, it was a 94% increase to $12.6 billion, nearly half of which was AI chip sales. These are used by giants such as Meta, Microsoft and IBM in their AI models. While AMD's 2025 forecast is positive with strong double-digit growth expected in data centres, the current quarter's estimate of a 7% drop in sales was not such good news for the markets.
The overall results were good
Although AI revenue was not as expected, AMD's overall results were better. In the final three months of last year, AMD delivered adjusted earnings per share (EPS) of $1.09 on revenue of $7.66 billion. The numbers beat the forecasts of LSEG analysts, who were expecting revenue of $7.53 billion on EPS of $1.08. For the quarter, the company's net income fell to $482 million, down from $667 million in the same period last year. In addition, AMD's revenue from its client business, which includes chips for PCs and notebooks, increased 58% year-over-year, driven by strong demand. The gaming division, on the other hand, faced setbacks, with revenues falling 59% to $563 million. This was due to a drop in sales of processors to Sony and Microsoft. AMD's outlook for the first quarter of 2025 forecasts sales of around $7.1 billion with a gross margin of around 54% and further hopes for a stronger product offering in 2025. [1]
Google will spend even more on AI
California's Alphabet hasn't delivered the desired news from its AI business either. Not only did it report disappointing cloud services revenue, but question marks about the sustainability of its profitability have also raised significantly higher capital expenditure for 2025. Parent company Google revealed that it plans to spend $75 billion on artificial intelligence, significantly more than it did last year, when it spent "only" $52.5 billion. The latest figure even surpassed expectations of $58 billion. Although Alphabet remains confident that AI will deliver significant long-term benefits, investors' concerns have been exacerbated by the slower-than-expected growth of the cloud division. It grew just 30% to nearly $12 billion, down from 35% in the previous quarter and below what LSEG analysts had expected, according to Reuters. The company attributed this to an imbalance between demand for its AI-related services exceeding its capacity.
Did not meet expectations
Alphabet's fourth-quarter 2024 financial results, also released on February 4, 2024, showed solid profitability but fell short of expectations. The giant did report a net profit of $26.5 billion with EPS of $2.15, up 28% from the previous year. However, revenue growth slowed down slightly. These rose 12%, to $96.47 billion, compared to 13% in the same period last year. LSEG had expected revenues to be slightly higher, at USD 96.56 billion. Core advertising activity, including search and YouTube ads, also grew, but more modestly than the prior year, reflecting a more competitive digital advertising environment. The company did not disclose financial forecasts for the period ahead. Alphabet is not only focusing on these areas, but is also expanding the reach of its Waymo subsidiary, which operates autonomous taxis. In addition to Los Angeles and San Francisco, the services are also available in Texas, and as part of an international expansion, the taxis are expected to arrive in Tokyo.
Negative impact on shares
The technology sector continues to be dominated by artificial intelligence, with the imaginary bar for its profitability being raised every quarter. The disappointing results and forecasts of both companies caused their shares to plummet after the market closed on 4 February 2025.* AMD saw a decline of almost 9%, while Alphabet, which had previously reached a new high, lost 6.5%. Losses extended during trading hours on February 5, 2025.* The value of Alphabet shares fell further after the market opened to $192.39 and AMD dropped to $107.01.* Comparing the values to the same period last year, Alphabet shares rose 38%.* In contrast, AMD saw a year-over-year decline of as much as 30%. From a 5-year perspective, both companies were in the green.*
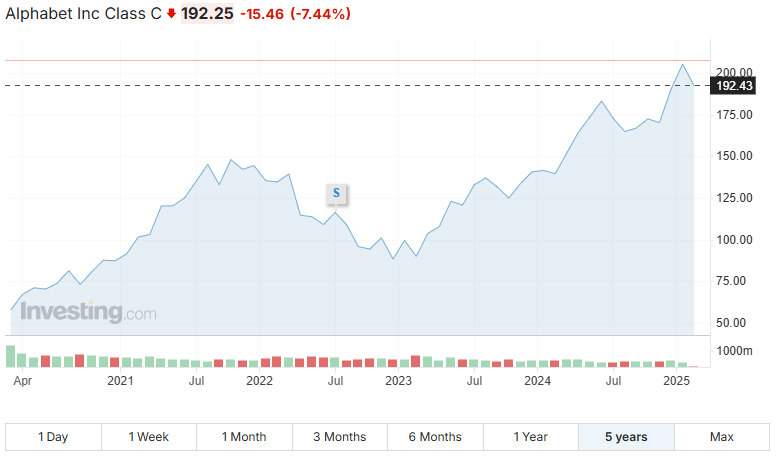
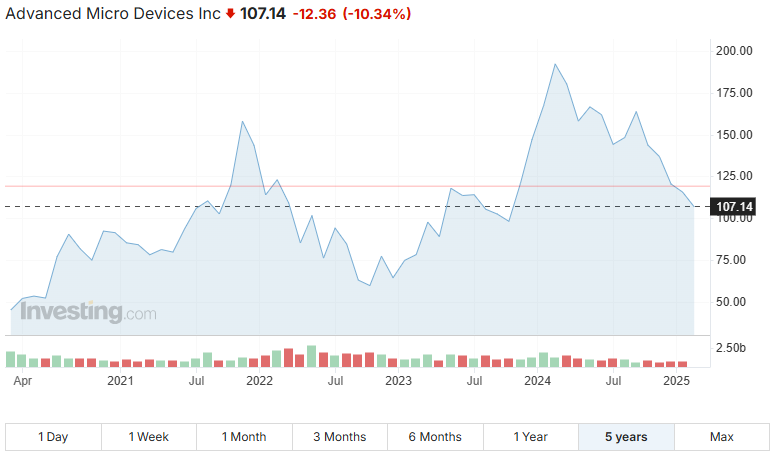
Source: Investing.com*
Conclusion
The data center and artificial intelligence sector remains a key battleground for tech giants, but current market expectations seem relentless. While AMD and Alphabet are investing in the future, investors are looking at near-term results with increasing skepticism. Unless they can convince the markets of sustainable profitability, their share price fluctuations may continue. Developments suggest that the ability of technology firms to not only innovate, but also to effectively monetise their advanced technologies, will continue to be a critical factor in 2025.
* Past data is not a guarantee of future returns.
[1] Forward-looking statements are assumptions and current expectations that may not be accurate or are based on the current economic environment, which may change. These statements are not guarantees of future performance. Forward-looking statements, by their nature, involve risk and uncertainty because they relate to future events and circumstances that cannot be predicted and actual developments and results may differ materially from those expressed or implied by any forward-looking statements.
Warning! This marketing material is not and should not be construed as investment advice. Past data is not a guarantee of future returns. Investing in foreign currency may affect returns due to fluctuations. All securities transactions may result in both gains and losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which may change. These statements are not guarantees of future performance. InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s. regulated by the National Bank of Slovakia.
Sources:
https://abc.xyz/assets/a3/91/6d1950c148fa84c7d699abe05284/2024q4-alphabet-earnings-release.pdf
https://www.digitimes.com/news/a20250205VL204/amd-lisa-su-earnings-data-center-2025.html
https://finance.yahoo.com/news/amd-data-center-sales-miss-214423845.html
https://www.cnbc.com/2025/02/04/amd-earnings-report-q4-2024.html
https://www.cnbc.com/2025/02/04/alphabet-q4-earnings-report-2024.html



