Back to blog

Dell in the Era of Artificial Intelligence: Beating Expectations and Billion-Dollar Revenue Forecasts

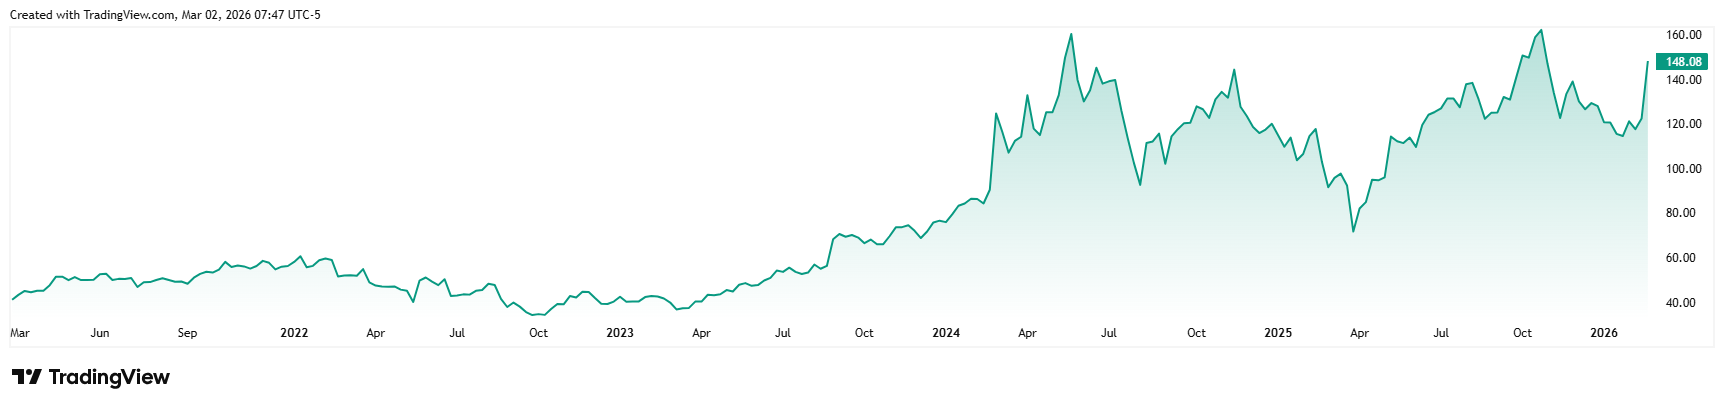
Just a few years ago, Dell was primarily seen as a reliable supplier of office equipment and personal computers. However, in 2026, this technological veteran has definitively transformed into a key player in artificial intelligence infrastructure, as confirmed by its latest financial results. Following the release of the report for the fourth fiscal quarter, Dell's shares responded with a rocket-like increase of 22%,* sending a clear signal that the market has enormous confidence in its new strategy.

Dell in the Era of Artificial Intelligence: Beating Expectations and Billion-Dollar Revenue Forecasts
Financial Strength


In the past quarter, Dell not only met the expectations of analysts surveyed by the London Stock Exchange Group (LSEG) but exceeded them in many areas. Starting with earnings per share (EPS), it increased to 3.89 USD, significantly surpassing the market estimate of 3.53 USD. Similarly, revenues saw a positive development, increasing by nearly 40% year-on-year, reaching 33.38 billion USD, exceeding analysts’ consensus by over 1.5 billion USD.

DELL_2026-03-02_13-47-35


Performance of Dell’s stock price over the last five years


Dell’s fundamental strength for 2026 undoubtedly pleased investors, but the primary trigger for the subsequent stock price growth was the outlook for the upcoming fiscal year 2027. While the market had set the revenue forecast at just under 125 billion USD, Dell’s management confidently set the bar at 138 to 142 billion USD. This optimism stems primarily from the demand for AI servers, which are expected to generate 50 billion USD in revenue by 2027, more than double compared to the previous year. [1]


The Battle for Memory


The tech world is currently facing a historic shortage of memory chips, which is creating significant tension across the sector. Memory manufacturers are prioritizing high-bandwidth memory (HBM) components for chipmakers like Nvidia and AMD, or for cloud giants like Google. This leaves traditional hardware manufacturers with limited components, leading to longer delivery times and drastic price increases.


Dell has approached this crisis proactively and has already begun raising prices for its products in the past year. CFO David Kennedy clarified that these steps were necessary to offset higher costs and protect the company's margins. COO Jeff Clarke emphasized that the key to success lies in close collaboration with partners, which allows Dell flexibility in its supply chain, setting it apart from competitors who often struggle with unpreparedness for price shocks.


Market Divergence


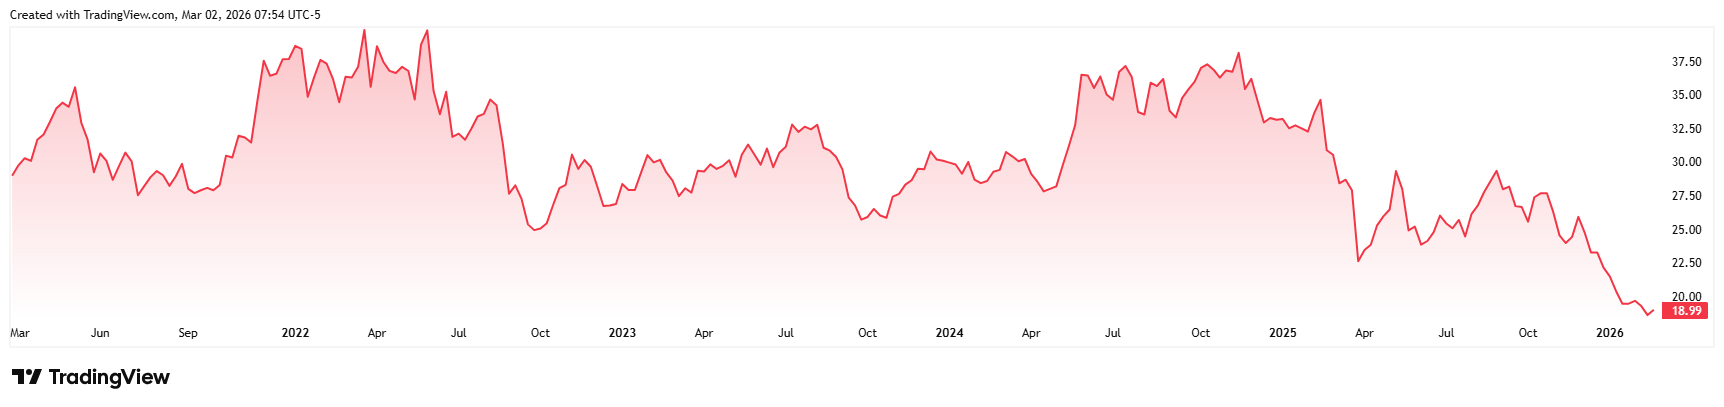
Looking at the competitive environment, the contrast between the major players is striking. While Dell is growing based on fundamental parameters, HP’s stock has fallen to its 52-week low. * The primary problem for HP is that memory costs now account for approximately 35% of the total cost of manufacturing a computer, double what it was a year ago. The inability to pass on this 100% increase in costs to the end customer has unfortunately exposed the vulnerability of their business model.

HPQ_2026-03-02_13-54-39


Performance of HP’s stock price over the last five years


Bank of America, while highlighting the risk of demand elasticity, or concerns that too-expensive computers may deter some customers, nonetheless raised its target price for Dell shares from 135 USD to 155 USD with a maintained "Buy" recommendation. [1] Unlike HP, Dell has successfully transformed its identity from a hardware vendor to a provider of comprehensive AI solutions, securing its place in institutional investors' portfolios.


Conclusion


If Dell succeeds in meeting its ambitious goal of doubling revenue from AI servers, it could become a fundamental pillar of infrastructure in the new digital era. Although questions remain about how long customers will be willing to accept rising hardware prices, the current dynamics clearly play in favor of this long-established Texas legend.


*Past performance is not a guarantee of future results.


[1] These statements do not guarantee future performance. Forward-looking statements inherently involve risks and uncertainties, as they relate to future events and circumstances that cannot be predicted, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.


Disclaimer! This marketing material is not and must not be construed as investment advice. Data related to the past are not a guarantee of future returns. Investing in foreign currency may affect returns due to fluctuations. All securities transactions may result in both gains and losses. Forward-looking statements represent assumptions and current expectations that may be inaccurate or based on the current economic environment, which may change. These statements do not guarantee future performance. InvestingFox is a trade name of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia.


Sources:


https://investors.delltechnologies.com/

https://investors.delltechnologies.com/static-files/cbb4c668-2613-4d5c-a7dc-98fe4592b5a5

https://www.cnbc.com/2026/02/27/dell-stock-earnings-memory-shortage-ai-servers.html

InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.

CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia -PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.

Read more

JPMorgan Chase Disappoints Wall Street: Even a Profit of $15.3 Billion Fell Short of Expectations

JPMorgan Chase Disappoints Wall Street: Even a Profit of $15.3 Billion Fell Short of Expectations

JPMorgan Chase zveřejnil 13. října výsledky za třetí čtvrtletí roku 2026, které pro Wall Street znamenaly neobvyklé zklamání. Největší americká banka vykázala zisk 5,57 USD na akcii oproti odhadu 5,85 USD a podle údajů LSEG poprvé od posledního čtvrtletí roku 2023 nesplnila prognózy zisku. Slabší výnosy z dluhopisových trhů a zpomalení investičního bankovnictví ukázaly, kde naráží její růst na omezení. Pro investory je nyní zásadní, zda banka dokáže udržet růst výnosů a zároveň zvládnout rostoucí náklady.1

Lamb Weston Surprises the Stock Market: Profit Falls 55%, Shares Jump 7.5%

Lamb Weston Surprises the Stock Market: Profit Falls 55%, Shares Jump 7.5%

Frozen french fry manufacturer Lamb Weston announced its results on October 6, 2026, revealing a striking discrepancy between reported profits and the stock market’s reaction. Net income plummeted 55% year-over-year, yet investors responded by buying shares. The company exceeded expectations and raised its full-year outlook. Sales growth in North America and cost-cutting measures suggest that changes in the company’s operations are beginning to pay off. The question remains, however, whether this progress will be enough to resolve problems overseas. [1]

TD SYNNEX Far Exceeded Expectations: Revenue Jumped 38%, but Shares Fell After the Earnings Report

TD SYNNEX Far Exceeded Expectations: Revenue Jumped 38%, but Shares Fell After the Earnings Report

TD SYNNEX reported results that, at first glance, look very strong and confirm that the company is benefiting from growing demand for technology infrastructure. Upon closer inspection, however, the picture is not entirely clear-cut. Behind the record numbers lies a combination of rapid expansion, shifting margins, and significant cash flow fluctuations, which investors have begun to view with far greater sensitivity than revenue growth alone. It is precisely the difference between what the income statement shows and what is happening beneath the surface that makes TD SYNNEX’s latest quarter a much more interesting story than the headline numbers alone would suggest.

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone closed fiscal year 2026 with results that appear very strong at first glance. Fourth-quarter revenue rose 5.6% year-over-year to $6.59 billion, net income increased to $931.6 million, and earnings per share reached $56.05, approximately 15% higher than a year ago and above Wall Street expectations. Beneath the surface, however, a weakness remains. Comparable sales growth fell short of forecasts, and American DIY car repairers continue to curb their purchases.1