Back to blog

Gen Z Darling in Trouble: As Pinterest’s Popularity Hits Records, Investors Count Losses

In the investment world, it is generally true that even a historical maximum in platform popularity may not be enough if unfavorable macroeconomics come into play. Pinterest is currently at exactly this paradoxical point. Although its ecosystem has never been more extensive, Q4 financial results and an uncertain outlook for early 2026 triggered a wave of sell-offs.

Gen Z Darling in Trouble: As Pinterest’s Popularity Hits Records, Investors Count Losses
Results Below Expectations

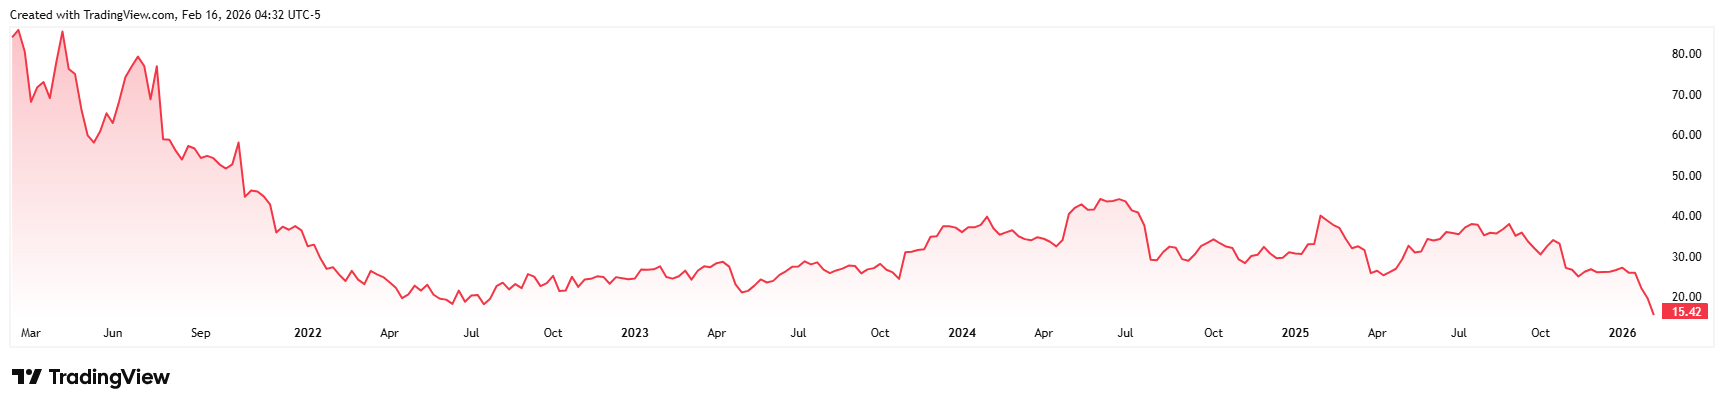
Pinterest closed the past quarter with revenue of $1.32 billion, narrowly missing estimates from analysts surveyed by the London Stock Exchange Group (LSEG) at $1.33 billion. However, the most significant hit was to net profit, which reached $277 million. This represents a significant 85% year-over-year drop, as the company managed a profit of $1.85 billion in the previous year. Lastly, the adjusted EBITDA figure of $541.5 million failed to meet analyst expectations. Combined with a weak Q1 outlook (projecting revenue below the analyst-expected $980 million threshold), this resulted in a nearly 20% drop in stock price on Friday.*
PINS_2026-02-16_10-32-42

Pinterest stock price performance over the last five years*

Impact of Global Tariffs

The main cause of Pinterest's weakened financial performance is not user interest, as many investors likely think, but a specific external factor. CEO Bill Ready has spoken openly about challenges related to tariffs. Pinterest holds a specific position compared to its competitors—its advertising portfolio consists largely of major retailers. These retailers are most affected by new tariffs, which subsequently forced them to immediately and significantly cut digital advertising spend. This high exposure to retail makes Pinterest much more vulnerable to trade decisions than other giants operating in this segment.

Bet on AI

Company management is responding decisively to this unfavorable environment. In January, Pinterest announced a plan to lay off nearly 15% of its employees to increase efficiency. The changes also include a reduction in office space. However, the saved capital isn't just going into savings—according to management, capital expenditures are being directed toward AI. In other words, financial resources are being massively shifted to development teams working on next-generation algorithms for better product targeting and content personalization, aimed at driving profitability in the medium term.

The Power of Gen Z

Despite the financial risks mentioned above, the fundamental side—represented by the user base—remains exceptionally strong. The number of monthly active users grew by 12% year-over-year to a record 619 million. Critically for the future, Gen Z is the fastest-growing demographic group on the platform. This group views Pinterest not only as a place for inspiration but increasingly as a tool for direct shopping, which ultimately confirms the strategic direction toward the platform's e-commerce features.

Investment Perspective

The current situation has split leading investment banks into two camps. Citi downgraded the stock to Neutral, reflecting immediate risks associated with macroeconomic instability. On the other hand, Goldman Sachs acknowledges short-term headwinds but remains optimistic for the long term. For investors, the key question is whether the 20%+ correction is an overreaction to temporary macroeconomic influences or a signal of deeper structural problems. However, if Pinterest successfully integrates AI into its business model and maintains the favor of the younger generation, the current decline may be seen as a risky but potentially advantageous entry point for those who believe in the future of visual search.[1]

[1] Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which is subject to change. These statements do not guarantee future performance. Forward-looking statements by their nature involve risk and uncertainty because they relate to future events and circumstances that cannot be predicted, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.

* Past performance data is no guarantee of future returns.

Sources:

https://investor.pinterestinc.com/financials/quarterly-results/default.aspx https://s204.q4cdn.com/369458543/files/doc_earnings/2025/q4/earnings-result/Q425-PressRelease.pdf

https://s204.q4cdn.com/369458543/files/doc_earnings/2025/q4/presentation/2025-Q4-IR-Earnings-Presentation.pdf

https://www.cnbc.com/2026/02/13/-pinterest-stock-price-tariff-earnings-layoffs.html

InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.

CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia -PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.

Read more

JPMorgan Chase Disappoints Wall Street: Even a Profit of $15.3 Billion Fell Short of Expectations

JPMorgan Chase Disappoints Wall Street: Even a Profit of $15.3 Billion Fell Short of Expectations

JPMorgan Chase zveřejnil 13. října výsledky za třetí čtvrtletí roku 2026, které pro Wall Street znamenaly neobvyklé zklamání. Největší americká banka vykázala zisk 5,57 USD na akcii oproti odhadu 5,85 USD a podle údajů LSEG poprvé od posledního čtvrtletí roku 2023 nesplnila prognózy zisku. Slabší výnosy z dluhopisových trhů a zpomalení investičního bankovnictví ukázaly, kde naráží její růst na omezení. Pro investory je nyní zásadní, zda banka dokáže udržet růst výnosů a zároveň zvládnout rostoucí náklady.1

Lamb Weston Surprises the Stock Market: Profit Falls 55%, Shares Jump 7.5%

Lamb Weston Surprises the Stock Market: Profit Falls 55%, Shares Jump 7.5%

Frozen french fry manufacturer Lamb Weston announced its results on October 6, 2026, revealing a striking discrepancy between reported profits and the stock market’s reaction. Net income plummeted 55% year-over-year, yet investors responded by buying shares. The company exceeded expectations and raised its full-year outlook. Sales growth in North America and cost-cutting measures suggest that changes in the company’s operations are beginning to pay off. The question remains, however, whether this progress will be enough to resolve problems overseas. [1]

TD SYNNEX Far Exceeded Expectations: Revenue Jumped 38%, but Shares Fell After the Earnings Report

TD SYNNEX Far Exceeded Expectations: Revenue Jumped 38%, but Shares Fell After the Earnings Report

TD SYNNEX reported results that, at first glance, look very strong and confirm that the company is benefiting from growing demand for technology infrastructure. Upon closer inspection, however, the picture is not entirely clear-cut. Behind the record numbers lies a combination of rapid expansion, shifting margins, and significant cash flow fluctuations, which investors have begun to view with far greater sensitivity than revenue growth alone. It is precisely the difference between what the income statement shows and what is happening beneath the surface that makes TD SYNNEX’s latest quarter a much more interesting story than the headline numbers alone would suggest.

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone closed fiscal year 2026 with results that appear very strong at first glance. Fourth-quarter revenue rose 5.6% year-over-year to $6.59 billion, net income increased to $931.6 million, and earnings per share reached $56.05, approximately 15% higher than a year ago and above Wall Street expectations. Beneath the surface, however, a weakness remains. Comparable sales growth fell short of forecasts, and American DIY car repairers continue to curb their purchases.1